A three-member bench of the Court of Appeal has ruled in favour of businessman Hassan Basajjabalaba and others that the Bank of Uganda (BOU) has no legal mandate to institute and defend court cases for purposes of recovering taxpayers’ funds on behalf of the Government of Uganda because that mandate is exclusively vested in and is a preserve of the Attorney General.
The apex court also held that:
- When a party (assignor) “absolutely and forever” assigns (transfers) their interest to another party (assignee), they lose the right and capacity to institute or defend a court case based on that assignment because the assignee will have become the interest holder vested with such right and capacity – if the same is not reserved under the assignment.
- A consent judgment is a contract between the parties to it, and once it has been endorsed by a Court of competent jurisdiction, it becomes a Judgment of that Court with its terms carrying the same weight as a decree of Court enforceable by execution.
- Striking out a party in a court case has the same practical effect as dismissing a case as against that party in an ordinary hearing or appeal, and as such there is no other “cause” left for that party to prosecute or defend.
- While the Court has the discretion to order that any person be joined as a party to proceedings before it if it is necessary to do so, such discretion must be exercised judiciously, and the Court should not descend into the arena of litigation by forcing any person to sue.
Key Background
In 2002, a company named Basajjabalaba Hides and Skins Limited (“the Company”) obtained two loans from two different commercial banks – Stanbic Bank and Standard Chartered Bank.
These loans were respectively guaranteed by different individuals, including but not limited to: Hassan Basajjabalaba, Mary Basajjabalaba, Iddi Basajjabalaba, among others.
The company defaulted on repayment, and after the default, the two commercial banks assigned all the rights in the loans and collateral to the Bank of Uganda, including the right to demand, sue, recover, enforce payment and take any other necessary steps to recover the debt.
In exchange, the Bank of Uganda paid these banks money as “consideration” for the assignment. For Standard Chartered, this money was USD 9,150,000. And for Stanbic Bank, it was USD 2,425,000.
Subsequently, a dispute arose, with the company suing the commercial banks and the Bank of Uganda via HCCS OS No.09/2005.
This case concerned the debts and the collateral provided to secure them.
The case was entirely settled by the parties by executing a consent judgment, which was endorsed by the High Court on 3rd February, 2010.
Under the consent judgment, it was agreed by the parties that the company would pay the Bank of Uganda – “for the benefit of the Government of Uganda,” a discounted or compromised amount of USD 11,575,000, including the amounts mentioned above that Bank of Uganda had paid the commercial banks to acquire the loans.
Otherwise, in case of default, the parties agreed that Bank of Uganda would be at liberty to recover the debts against the collateral provided by the company.
Following the consent judgement, the company filed an application via HCMA No.238 of 2011 against the Bank of Uganda and the Commissioner for Land Registration as a “nominal party” seeking “consequential orders,” namely the release of the property that had been mortgaged or provided as security for the loans, arguing that the agreed-upon (in the consent judgement) sum of USD 11,575,000 had been fully paid.
The company’s application was allowed by the High Court (Justice Wilson Kwesiga) after being satisfied that indeed USD 11,575,000 had been paid, thereby ordering Bank of Uganda to release about 18 land titles back to the company.
Subsequently, the two commercial banks together with Bank of Uganda instituted two separate “summary suits” under summary procedure against the above-mentioned individuals who had guaranteed these loans – “the guarantors,” in order to recover from the guarantors a total amount of USD 40,261,020.
The guarantors applied for leave to appear and defend the summary suits as is required under summary procedure, which was granted, and they proceeded to file their defence.
The guarantors then went ahead and filed an application via High Court Miscellaneous Application No.234 of 2013 against the Bank of Uganda, Stanbic Bank and Standard Chartered Bank, under which they asked the High Court to dismiss the suits had been “consolidated” for they were related, arguing that because of the assignment, the commercial banks no longer had “locus” (standing/capacity) to bring a court case to recover the loans.
Secondly, the guarantors argued that Bank of Uganda could not bring the case against them purporting to recover money belonging to the Government of Uganda because that authority is a constitutional preserve of the Attorney General.
Thirdly, that the suits did not disclose a “cause of action” against them – in other words, that the banks and Bank of Uganda did not a right that had been violated and that they, as the guarantors, were not responsible for that violation.
And lastly, the guarantors argued that the suits were “res judicata” because the question relating to the indebtedness of the company had been settled under the consent judgement and could therefore not be re-litigated.
The High Court decided the application as follows:
- That the assignment of the loans by the commercial banks to Bank of Uganda was absolute and that upon the assignment the banks had relinquished all their rights in the loan monies and therefore had no capacity/right to bring the suits. The Court went ahead to strike them out as parties to the suits.
- That Bank of Uganda, unlike the commercial banks, had the capacity to sue – getting this from the deed of assignment (the agreement to assign) and from Section 2(2) and (4) of the Bank of Uganda Act, which provide that BOU enjoys corporate legal status with powers to sue and/or be sued in its name and for its overall functions as the central bank of Uganda.
- That the legal principle to the effect that an agent of a named or known principal cannot sue in its name for recovery of a debt belonging to the principal was not applicable because the principal-agent relationship between the Government of Uganda and Bank of Uganda was governed by the Statute (the Bank of Uganda Act)
- That the presence of the Attorney General in the suits was necessary to enable the Court to effectively and completely determine and settle all questions involved in line with Order 1 Rule 10 (2) of the Civil Procedure Rules and therefore the Attorney General be added as a Plaintiff in the suits.
- That since Bank of Uganda had capacity to sue, then there existed a cause of action
- That under the consent judgment, the money agreed upon was supposed to be paid within 6 months and, in default, the Bank of Uganda was at liberty to enforce recovery in accordance with the assignment against the collateral.
- That such enforcement by the Bank of Uganda would be in accordance with the assignment and not by executing the consent judgment.
- That if the payment of USD 11,575,000 had been made within the stipulated 6 months under the consent judgment, then the suits would be “res judicata”, but if the payments had not been made as agreed, then the suits would not be “res judicata” because in that case the issues for determination would be much wider.
- And finally, the Court, after considering the ruling of Justice Wilson Kwesiga alluded to above in HCMA No.238 of 2011 ruled that, there was in fact a difference in the parties [ note: the absence of the guarantors as parties to the consent judgement), and that the issues in the present suits in question were wider than the issue of payment of USD 11,575,000 that had been handled by Justice Wilson Kwesiga – meaning that two key elements (same parties, same issues) made the principle of “res judicata” inapplicable.
The Appeal
Bank of Uganda, the commercial banks on the one hand and the guarantors, on the other, separately appealed to the Court of Appeal and their appeals were consolidated since they touched on related matters.
In the Court of Appeal, Bank of Uganda and the commercial banks, firstly, argued that the High Court erred in law and fact by holding that they did not have a cause of action having assigned the company’s loans to the Bank of Uganda.
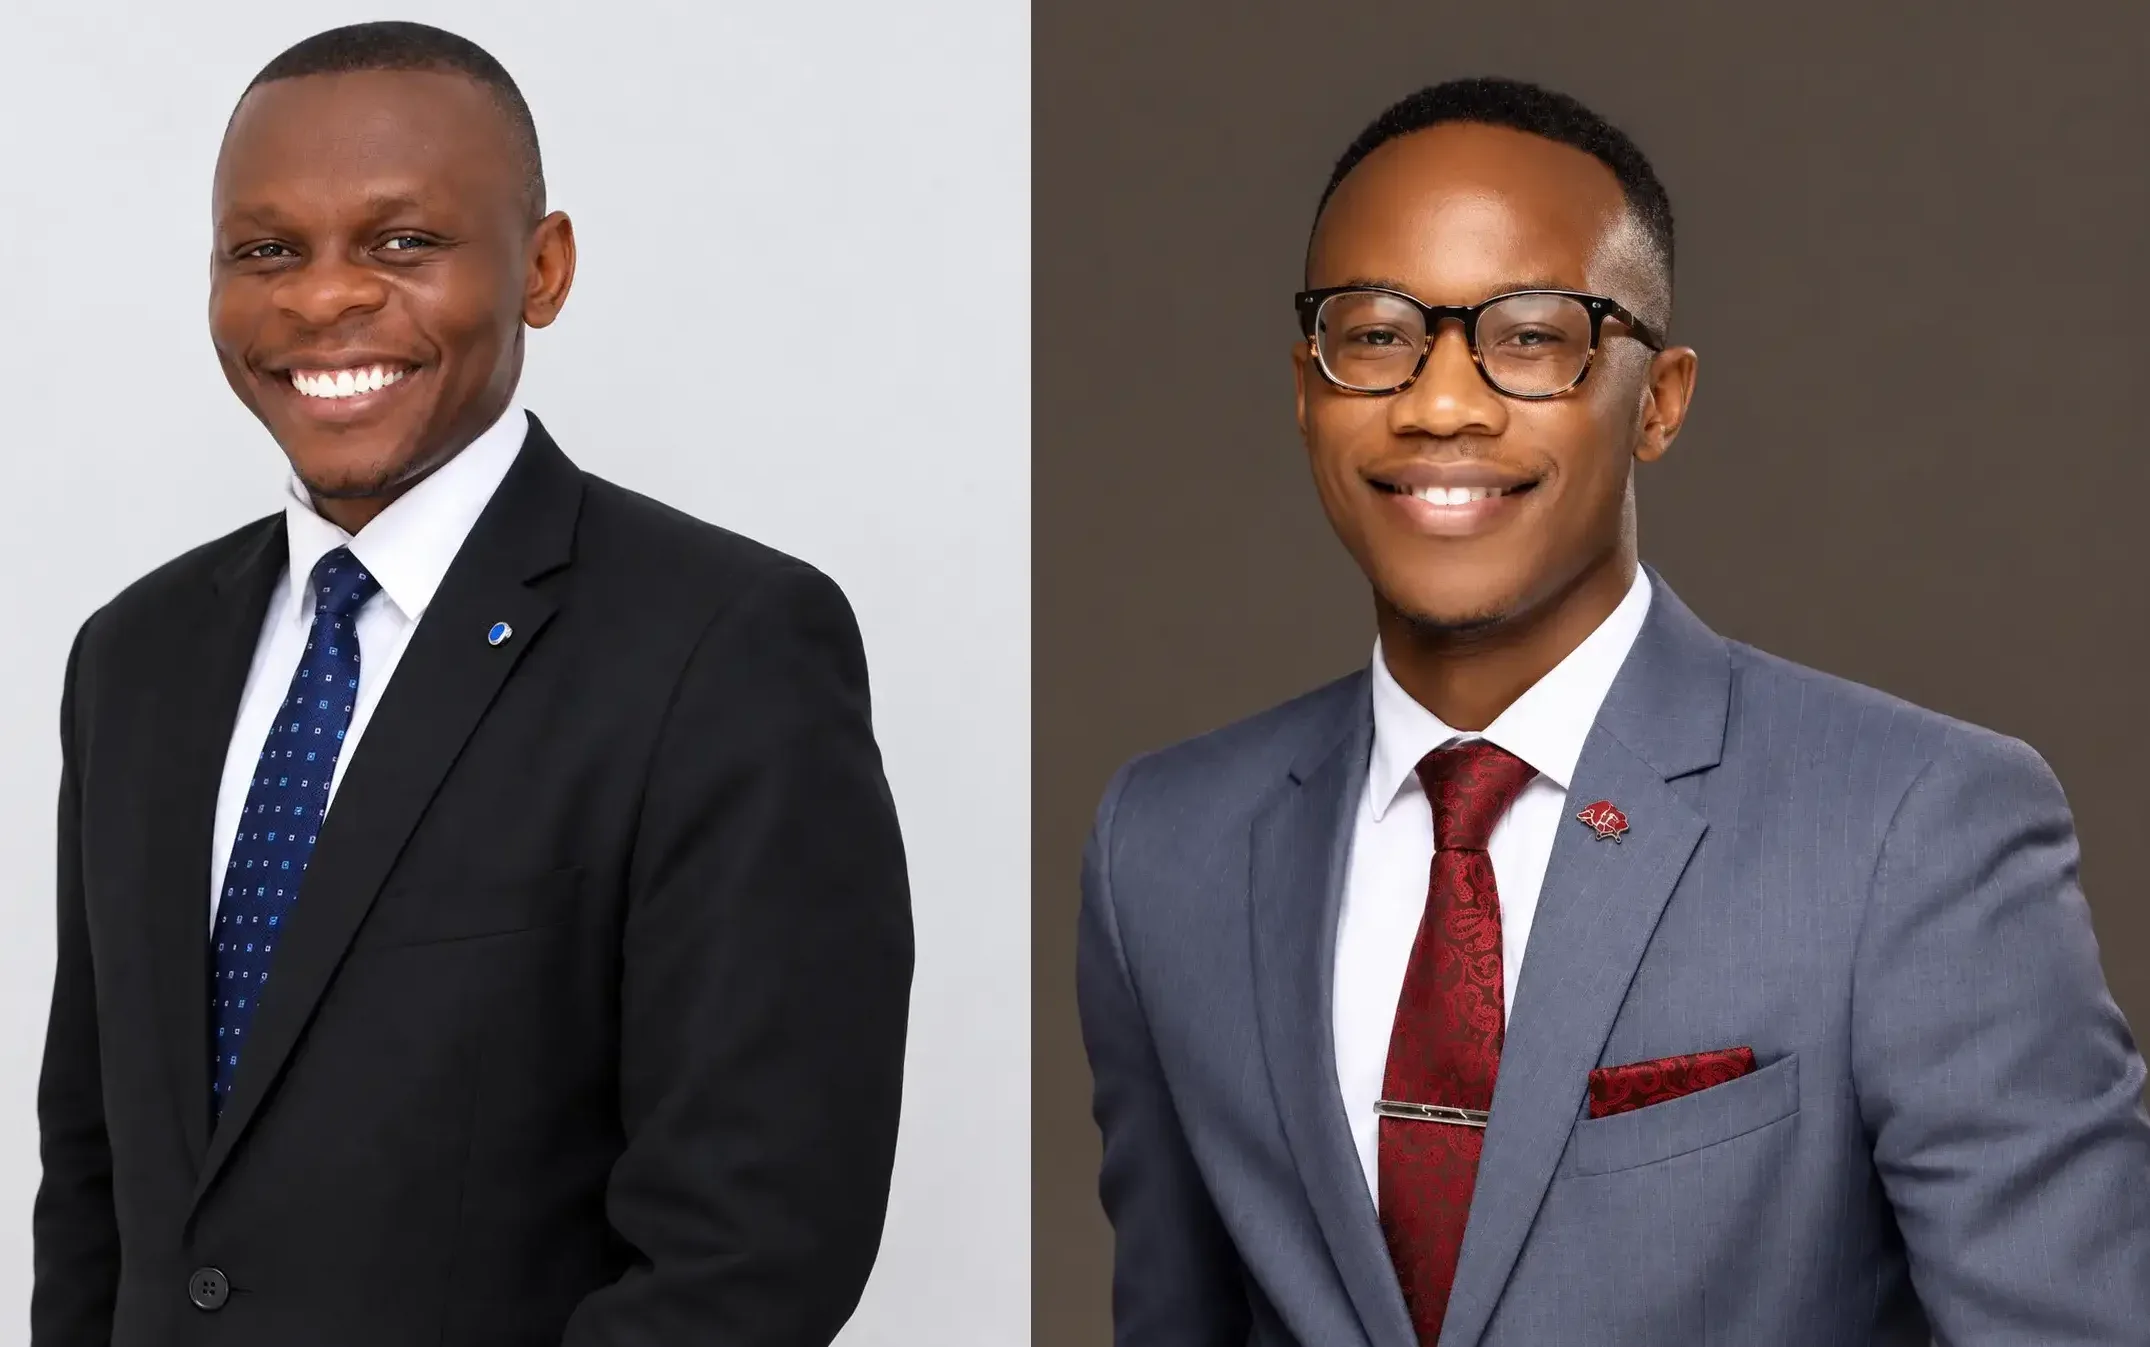
The banks, represented by Mr Joel Roy Mucunguzi from MMAKS Advocates (pictured right), holding brief for Mr Stephen Zimula, advanced the argument that:
- under the privity of contract doctrine, “only” entities or persons that are parties to a contract can derive rights to enforce such a contract and, as such, the assignment of the loans by the banks to the Bank of Uganda in exchange for consideration did not, as a matter of law, take away their cause of action held under the loan contract that they had entered into with the company. In the same breath, the attorney general, should not have been added as proper party to the proceedings because while the Bank of Uganda was recovering the money for the benefit of the government of Uganda, it was not doing so as its agent but as an assignee and as such the attorney general was not a party to the contract.
- The assignment of the loans to Bank of Uganda was an “equitable assignment” because there is no law in Uganda that provides for an assignment of a legal chose in action such as a debt (legal assignment). And in that case, an equitable assignee can bring proceedings to enforce a debt whether by itself alone or together with the assignor.
Secondly, the banks and Bank of Uganda argued that the High Court erred in law and fact when it held that the basis of Bank of Uganda’s entitlement to sue was because it is a statutory agent of the Government of Uganda.
They maintained the contention that the Bank of Uganda was a proper and necessary party to the recovery proceedings because, as much as it was collecting the money for the benefit of the government, it was not doing so in the context of a principal-agent relationship but rather as a contractual assignee.
It was wrong of the Judge therefore to attribute its entitlement to sue to the Bank of Uganda Act.
On their part, the guarantors challenged the decision of the lower court, on grounds that:
- The lower court judge erred in law and in fact when, after holding that Stanbic Bank and Standard Chartered Bank had no locus and no cause of action against them, thereby ordering that they be struck out of the case, she wrongly and injudiciously exercised her discretion by postponing the award of costs to the “main cause” or suit.
- The lower court judge erred in law and fact when she held that the Bank of Uganda has capacity to sue on behalf of the Government of Uganda, citing the Bank of Uganda Act.
- The lower court Judge erred in law and in fact when she held that the summary suits disclosed a cause of action by Bank of Uganda against them.
- The learned lower court Judge erred in law and in fact when she held that the consent judgment entered between the Banks, Bank of Uganda and the company did not render the summary suits “res judicata”.
- That the learned lower court Judge erred in law and fact when she ordered that the Attorney General be added as a Plaintiff to the suit by the commercial banks and Bank of Uganda.
Briefly, the running themes in arguments advanced by the guarantors’ lawyers – Mr Caleb Alaka of Alaka & Co Advocates together with Mr Joseph Kyazze of M/s Magna Advocates (pictured left) were as follows:
- Having found that the commercial banks had no locus standi (capacity to sue) or cause of action (reason or basis to sue) on account that they assigned or transferred their rights and interests in the loans given to the company – to the Bank of Uganda, she could not now purport to defer or postpone the award of costs for that successful application to the “main cause” or suit because the practical effect of such a finding and the resultant order that the banks be struck out as parties to the suits carried the same weight as a dismissal of their suit in an ordinary hearing or appeal – and therefore there was no further “cause” or suit in respect of the commercial banks but only in respect of the Bank of Uganda.
In doing so, the lower Court (High Court) Judge had exercised her discretion on the award of costs injudiciously, contrary to the law governing costs.
- There was nothing in the provisions of the Bank of Uganda Act, specifically Section 4, that the High Court Judge relied on to hold that the Bank of Uganda could sue on behalf of Government – that allocated such powers to BOU.
And even if they were, the Bank of Uganda Act became law on 14th May, 1993 before the present Constitution of Uganda and, as such, it had to be interpreted with necessary modifications to bring it into conformity with the Constitution which reserves this power in the hands of the Attorney General – in accordance with Article 274 of the same Constitution.
And in any case, parties to a contract cannot by such contracting allocate a constitutional power reserved for another party to a party to the contract because that would amount to usurpation of the Constitution – and as such, that contract would be illegal.
- The issues concerning the indebtedness of the company in question were settled by a consent judgement, and now bringing the same issues before the court in these summary suits offended the doctrine of Res Judicata enshrined in Section 7 of the Civil Procedure Act.
A consent judgement is a contract between the parties to it, and when it receives the endorsement or sanction of the Court, it becomes a judgement of that Court, thereby settling the issues in it in finality.
And a consent judgement cannot be challenged by “creatively” bringing another suit relating to the issues in it as between the same parties – it must be challenged through review or an application to set it aside on account of fraud, etc.
- The Bank of Uganda did not have any cause of action to sue the guarantors because, apart from having no such powers to sue, the issue of the loans it was demanding had been settled in the consent Judgement where it was agreed that the company in question pays the Central Bank a discounted or compromised sum of $11,575,000 – which was paid by the company.
And as such, the guarantors could not be sued where the principal debtor had actually paid back the loan money.
- While Order 1 Rule 10(2) of the Civil Procedure Rules allows the Court to order that any person be added as a party to a matter before the Court if it determines such a person is necessary for the court to determine the issues before it, the Court could not practically direct or order any person to sue another person because the decision to sue must be weighed independently by such a person.
And as such the Court could not order the Attorney General to be added to the summary suits as a plaintiff, much as the money sought to be recovered was public funds – doing so would undermine the independence of the Attorney General and would amount to the Judiciary fettering the independence of the Executive arm of the Government contrary to the doctrine of separation of powers.
Decision of the Court
The Court of Appeal, comprising Justice Eva Luswata, Justice Florence Nakachwa and Justice Musa Ssekaana, agreed entirely with the arguments of the guarantors thereby allowing their appeal.
The Court also partially allowed the appeal of the commercial banks to the extent that Bank of Uganda did not have capacity to sue as a statutory agent of the Government.
It is important to note at this point that the way the appeals of the commercial bank and the guarantors of the company’s loan were framed was such that they generally seemed to have the same argument on Bank of Uganda’s capacity to sue on behalf of Government but for different reasons as indicated above.
The commercial banks’ argument was that Bank of Uganda’s capacity to sue was based on the contract of assignment of the loans to it and not the Bank of Uganda Act as the High Court had decided.
The Court of Appeal therefore partially dismissed the commercial bank’s appeal and entirely allowed the guarantors’ appeal.
Justice Musa Sekaana analysed the deeds of assignment in question, the Bank of Uganda Act, the consent Judgement, and relevant case and statute law and delivered the Judgment of the Court on 15th September, 2026 as follows:
- The two commercial banks had no cause of action in the suits having assigned their interests in the debts of the company and its securities to Bank of Uganda.
Under the deeds of assignment and the subsequent consent judgment, the banks had not reserved the right to recover the debts and had handed the same “absolutely” to Bank of Uganda.
Nothing in the consent judgement showed that the parties agreed that in case of default by the company, the parties should return to their pre-consent status – where the banks could demand more money than that agreed in the consent.
In case of default by the company, the Bank of Uganda, being the assignee, had to pursue execution of the consent judgment by attaching and selling the collateral.
Principle of law:
- A court of law must treat as sacrosanct a lawful contract entered into by the parties and must reject the invitation to read into the contract terms other than those agreed to by the parties.
- A consent judgment which has been endorsed by the Court constitutes an order or decree of the Court and binds the parties and their privies and supersedes any earlier claims, agreements, correspondence and pleadings.
- An objection as to locus standi goes to the very root of the cause of action. If it is successful, it marks the end of the matter.
- Bank of Uganda did not have a cause of action to bring the summary suits in question against the guarantors;
First, as indicated above, the consent judgment had settled the issues relating to the money being sought in the suits because it “supersedes any earlier claims, agreements, correspondence and pleadings.”
Secondly, the Bank of Uganda Act, specifically Section 4(2) relied on by the High Court Judge, does not confer any powers on the central bank to bring or defend any suits on behalf of the government.
The powers (corporate personality) to sue and be sued in its name conferred on the Bank of Uganda do not extend to debt recovery proceedings on behalf of the Government.
And as such, that power is limited to the ordinary functions of the central bank such as maintaining monetary stability, issuing currency notes and coins, being the Banker of the Government, etc.
Principle of law:
- While a statutory body or institution of government may have corporate legal status, that status is limited to its legal functions and institutional interests.
- The Attorney General is the only competent person to sue for and on behalf of the Government of Uganda in line with Articles 119 (4) (c), and 250 (2) of the Constitution.
- The High Court Judge exercised her discretion injudiciously when she deferred to a non-existent “cause” or suit the decision on the award of damages to the guarantors, yet they were the successful parties in that application, having caused the striking out of the commercial banks in the summary suits (“following the event”).
Having been struck out as parties in the summary suits, the commercial banks were not left with any other “cause” to pursue or “defend” and as such the High Court Judge could not defer the award of costs to a non-existent cause or suit.
In doing this, the Judge did not assign or give reason for her decision because the principle of law on costs as enshrined in Section 27 of the Civil Procedure Act is that they “follow the event” which means that a successful party who asks for costs is ordinarily entitled to an award of costs unless there is “good reason” for denying the award.
In this case, there was no reason to deny the guarantors an award of costs, for they were successful in their application and as such the Judge’s decision was erroneous and injudicious.
Principle of law:
- Judicial discretion must be exercised judiciously, and while a Court on Appeal does not ordinarily interfere with the discretion of the court before it even if it thinks it would have exercised its discretion differently, it will do where such exercise of discretion is found to be erroneous and injudicious.
- A successful party is entitled to costs if he/she/it has asked (pleaded) for them and denial of such costs must be for good reason. The judicial officer must give the parties that reason.
- The summary suits by the commercial banks and Bank of Uganda were “Res Judicata” because the issues they raised had been settled by a competent court via its consent judgment as between the same parties or their privies or those under whom they claim and the same could not be resurrected.
Arguments that the amounts claimed in the summary suits were different and that the parties were different because the suits were against the guarantors failed.
Principle of law:
- The doctrine of Res Judicata works like an estoppel, stopping a party from subsequently instituting a suit against the same party(ies) or his/her/its privies or under whom they or any of them claim, litigating under the same title and raising the same issues that have already been determined by a competent court.
- The High Court Judge injudiciously exercised her discretion under Order 1 Rule 10 (2) of the Civil Procedure Rules when she ordered that the Attorney General be added as a plaintiff to the summary suits.
The Court of Appeal was unequivocal that: “In every situation where the court has discretion, that discretion must be exercised judiciously, which simply means applying the law taking into account the circumstances of the case.”
Thus, it found that the Judge’s decision to order that the Attorney General be added as a plaintiff in the summary suits resulted in a direct violation of the Constitutional right of the Attorney General to institute [or decline] cases on behalf of government in so far as it amounted to “dragging the Attorney General in matters or court cases which they are not prepared to pursue or have no interest to pursue by becoming a plaintiff.”
Principle of law: Judicial discretion must be exercised judiciously, and this involves considering the law and the circumstances of the case.
KEY QUOTE
“There is nothing in the above sections [of the Bank of Uganda Act, Cap.59) conferring locus upon the Bank of Uganda to sue for and on behalf of the Government and recover moneys allegedly due to the Government of Uganda arising out of private arrangements between the Government and ordinary persons and entities. I am of the view that Bank of Uganda’s power to sue under the said provisions are restricted to matters set out in the Act relating to performance of the Central Bank’s obligations and functions under Section 4 of the Act.” – Justice Musa Sekaana, Justice of the Court of Appeal. (Emphasis is mine)
Lawyers involved: Joel Roy Mucunguzi from MMAKS Advocates, holding brief for Mr Stephen Zimula (for the commercial banks and Bank of Uganda). Mr Caleb Alaka of Alaka & Co Advocates, together with Mr Joseph Kyazze of M/s Magna Advocates.
Check back with us for PDF full judgement. We are uploading it.
Benjamin is a Ugandan lawyer and legal eagle on commercial and corporate legal practice.